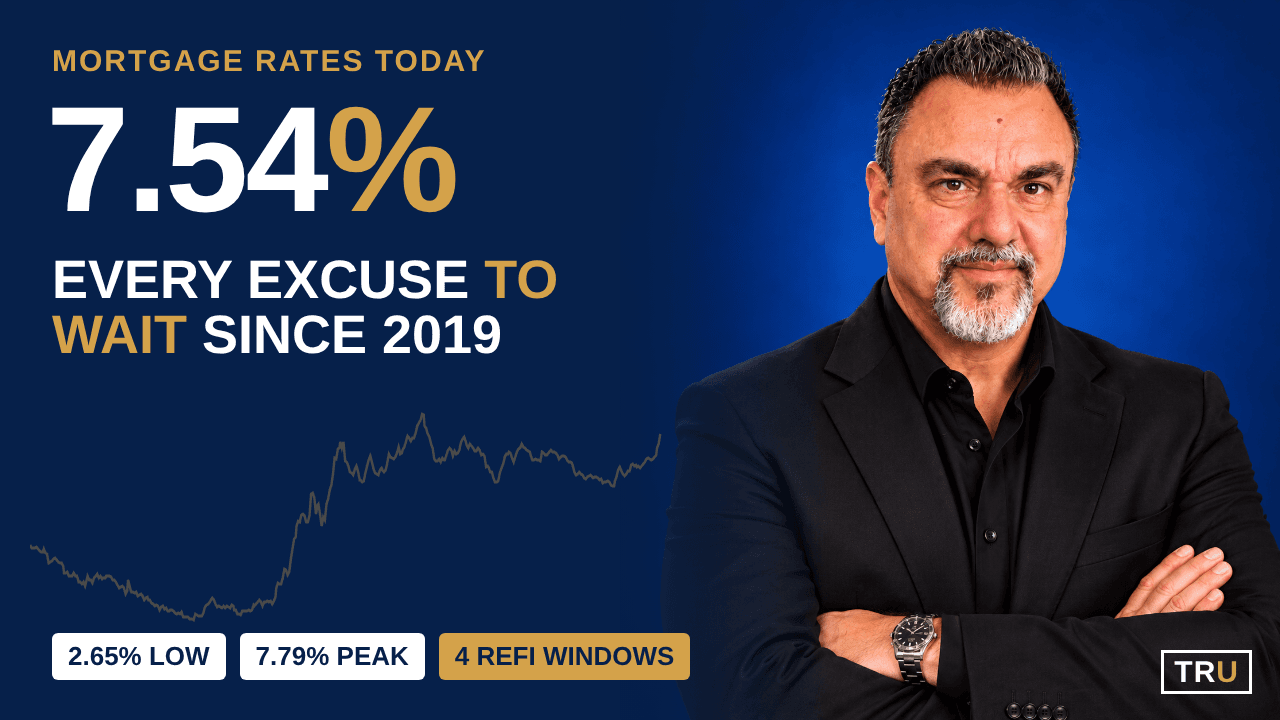
Every day on The Rate Update we talk about jobs, wages and inflation. Today let's talk about excuses. Since 2019 there has always been a reason to wait: a pandemic, a crash that never came, an election, tariffs and now a war. Here is what mortgage rates, the 10-year Treasury, the Federal Reserve and home prices actually did through each one, and the four times you could have refinanced.
| Measure | Latest | Context |
|---|---|---|
| 30-yr fixed, Mortgage News Daily | 7.54% | Daily index, Oct 1, 2026 close |
| 30-yr fixed, Freddie Mac weekly | 7.28% | Oct 1, 2026, highest since November 2023 |
| 10-year Treasury | 5.29% | Sep 30, 2026 close |
| Fed funds target | 3.75%–4.00% | Raised 0.25 on Sept 16–17, 2026 |
| CPI inflation | 3.4% | August 2026, year over year |
| Home prices since Jan 2019 | +65% | Case-Shiller National Index through July 2026 |
Gold: Freddie Mac 30-year fixed, weekly. Blue: 10-year Treasury, monthly average. Gray dashed: Fed funds upper target. Green bands: refinance windows. Sources: Freddie Mac PMMS, U.S. Treasury and Federal Reserve via FRED.
Rates started 2019 at 4.51% with the Fed at 2.50%. The Fed cut three times that year, and by February 2020 the 30-year was at 3.45%, before anyone had heard of COVID. Home prices still rose 4.4%.
The Fed cut to zero on March 15–16, 2020, and the 10-year Treasury fell to about 0.6%. Mortgage rates hit Freddie Mac's all-time record low of 2.65% on January 7, 2021. Instead of crashing, home prices rose almost 11% in that stretch.
With the Fed still at zero, home prices climbed another 25% between January 2021 and March 2022. Rates were still near 3% for most of 2021.
The Fed started raising rates on March 17, 2022 and raised 11 times in 16 months, from near zero to 5.50%. The 30-year went to 7.08% in November 2022 and peaked at 7.79% on October 26, 2023. Home prices dipped about 5% in the second half of 2022, then went on to new highs by mid-2023. That was the crash.
Rates fell from the 2023 peak to 6.08% the week after the Fed's first cut in September 2024. They did not reach 5%.
After the November 5, 2024 election the 10-year Treasury climbed from about 3.7% to 4.6%, and the 30-year rose from 6.08% to 7.04% by January 16, 2025, even though the Fed cut twice more.
The “Liberation Day” tariffs were announced April 2, 2025. Rates were 6.64% that week, jumped to 6.83% two weeks later and peaked at 6.89% in late May. Then they eased through the second half of the year as the Fed cut three more times, ending 2025 at 6.15%. By February 26, 2026 the 30-year was at 5.98%, the lowest weekly average in more than three years.
The war began February 28, 2026, two days after that low. Oil and inflation pressure pushed the 10-year Treasury from about 4.1% to 5.29%. CPI inflation ran 3.4% in August, and the Fed raised rates for the first time since 2023 on September 16–17. Freddie Mac's weekly average is now 7.28%, and Mortgage News Daily's daily index is 7.54%.
| Phase | Dates | 30-yr fixed | 10-yr Treasury | Fed funds (upper) | Home prices |
|---|---|---|---|---|---|
| Pre-COVID | Jan 2019 – Feb 2020 | 4.51% → 3.45% (−1.06) | 2.71% → 1.50% (−1.21) | 2.50% → 1.75% (−0.75) | +4.4% |
| COVID, Fed to zero | Feb 2020 – Jan 2021 | 3.45% → 2.65% (−0.80) | 1.50% → 1.08% (−0.42) | 1.75% → 0.25% (−1.50) | +10.9% |
| Boom, Fed still at zero | Jan 2021 – Mar 2022 | 2.65% → 4.16% (+1.51) | 1.08% → 2.13% (+1.05) | 0.25% → 0.50% (+0.25) | +24.7% |
| Fastest hikes in 40 years | Mar 2022 – Oct 2023 | 4.16% → 7.79% (+3.63) | 2.13% → 4.80% (+2.67) | 0.50% → 5.50% (+5.00) | +6.1% |
| Relief rally, first cut | Oct 2023 – Sep 2024 | 7.79% → 6.08% (−1.71) | 4.80% → 3.72% (−1.08) | 5.50% → 5.00% (−0.50) | +3.8% |
| The election | Sep 2024 – Jan 2025 | 6.08% → 7.04% (+0.96) | 3.72% → 4.63% (+0.91) | 5.00% → 4.50% (−0.50) | −0.3% |
| Tariffs | Jan 2025 – Feb 2026 | 7.04% → 5.98% (−1.06) | 4.63% → 4.13% (−0.50) | 4.50% → 3.75% (−0.75) | +1.3% |
| The Iran war | Feb 2026 – Oct 2026 | 5.98% → 7.28% (+1.30) | 4.13% → 4.99% (+0.86) | 3.75% → 4.00% (+0.25) | +2.9% |
| Whole period | Jan 2019 – Oct 2026 | 4.51% → 7.28% (+2.77) | 2.71% → 4.99% (+2.28) | 2.50% → 4.00% (+1.50) | +65.2% |
30-yr: Freddie Mac weekly average at the start and end of each phase. 10-yr: monthly average yield. Home prices: S&P CoreLogic Case-Shiller U.S. National Index (not seasonally adjusted), latest July 2026.
Case-Shiller U.S. National Home Price Index, percent change since January 2019. Source: S&P CoreLogic via FRED.
| Bought a $400,000 home in | Rate that week | Value today* | Change |
|---|---|---|---|
| January 2019 | 4.51% | $660,725 | +65.2% |
| January 2021 | 2.65% | $570,728 | +42.7% |
| June 2022 | 5.81% | $437,910 | +9.5% |
| October 2023 | 7.79% | $431,330 | +7.8% |
| January 2025 | 7.04% | $416,934 | +4.2% |
| February 2026 | 5.98% | $411,592 | +2.9% |
*Estimated using the national index through July 2026. Your local market will differ.
Even someone who bought at the worst rate of the cycle, October 2023 at 7.79%, has seen prices rise about 8% since. Anyone who bought before mid-2022 is up roughly 10% to 65%. The only real decline in this whole stretch was the second half of 2022, about 5%.
Each of these windows was a stretch when the weekly average sat well below where recent buyers had locked. Savings are principal and interest on a $400,000, 30-year loan.
| Window | Dates | Low | Example | Monthly savings | Yearly savings |
|---|---|---|---|---|---|
| 1 | Dec 2022 – Feb 2023 | 6.09% (Feb 2, 2023) | Bought Nov 2022 at 7.08% | −$261 | −$3,136 |
| 2 | Dec 2023 – Feb 2024 | 6.60% (Jan 18, 2024) | Bought Oct 2023 at 7.79% | −$322 | −$3,865 |
| 3 | Aug – Oct 2024 | 6.08% (Sep 26, 2024) | Bought May 2024 at 7.22% | −$302 | −$3,621 |
| 4 | Sep 2025 – Mar 2026 | 5.98% (Feb 26, 2026) | Bought Jan 2025 at 7.04% | −$279 | −$3,347 |
Window 4 was the longest: six months at or under 6.35%, from September 2025 into March 2026. It closed when the war started.
| Point in the cycle | 30-yr rate | P&I on $400,000 |
|---|---|---|
| Record low, Jan 7, 2021 | 2.65% | $1,612 |
| 2026 low, Feb 26, 2026 | 5.98% | $2,393 |
| Window 3 low, Sep 26, 2024 | 6.08% | $2,419 |
| Freddie Mac weekly, Oct 1, 2026 | 7.28% | $2,737 |
| Today, Mortgage News Daily | 7.54% | $2,808 |
| Cycle peak, Oct 26, 2023 | 7.79% | $2,877 |
Waiting from the February low to today has added about $344 a month on a $400,000 loan using Freddie Mac's weekly averages.
Every year had a reason to wait, and home prices kept rising anyway. The buyers who did best were the ones who bought a home they could afford and then refinanced when a window opened. The next window will come. The people who catch it are the ones who already know their numbers.
Set up a Rate Watch and we will alert you when rates hit your target, check live rates yourself, or book a free call. One application. One credit pull. 30+ mortgage lenders.
Freddie Mac's weekly 30-year fixed average hit its all-time low of 2.65% on January 7, 2021.
Freddie Mac's weekly average peaked at 7.79% on October 26, 2023. Some daily rate indexes briefly topped 8% around the same time.
The deepest window was September 2025 through early March 2026, when the 30-year averaged 6.35% or lower and bottomed at 5.98% on February 26, 2026. Shorter windows opened in early 2023, around the turn of 2024 and in September 2024.
Mortgage rates track the 10-year Treasury. Since the Iran war began, oil prices and inflation pressure have pushed the 10-year from about 4.1% to 5.29%, and the Fed raised its benchmark rate in September 2026.
Sources: Freddie Mac Primary Mortgage Market Survey; Mortgage News Daily 30-year fixed index; U.S. Treasury 10-year constant maturity yield; Federal Reserve target range; S&P CoreLogic Case-Shiller U.S. National Home Price Index (all via FRED, St. Louis Fed); U.S. Bureau of Labor Statistics CPI, August 2026.
Rates shown are national survey averages for education only and are not a rate quote, offer or commitment to lend. Payment examples are principal and interest only and exclude taxes, insurance, mortgage insurance and closing costs. A refinance has its own costs that affect whether it makes sense. Your rate depends on credit, loan amount, property, occupancy and program. Dan Frio | NMLS #246527 | PBT Bancorp | NMLS #257781. Mortgage products are originated by PBT Bancorp, NMLS #257781. 524 Main St, Hazard, KY 41701. Equal Housing Opportunity.