How much house can I afford? Most online affordability calculators give you an answer from your income and an interest rate. The number that actually decides your buying power also includes property taxes, homeowners insurance, HOA dues and the loan program you use. In the video above I ran a real buyer through the same math a lender uses.
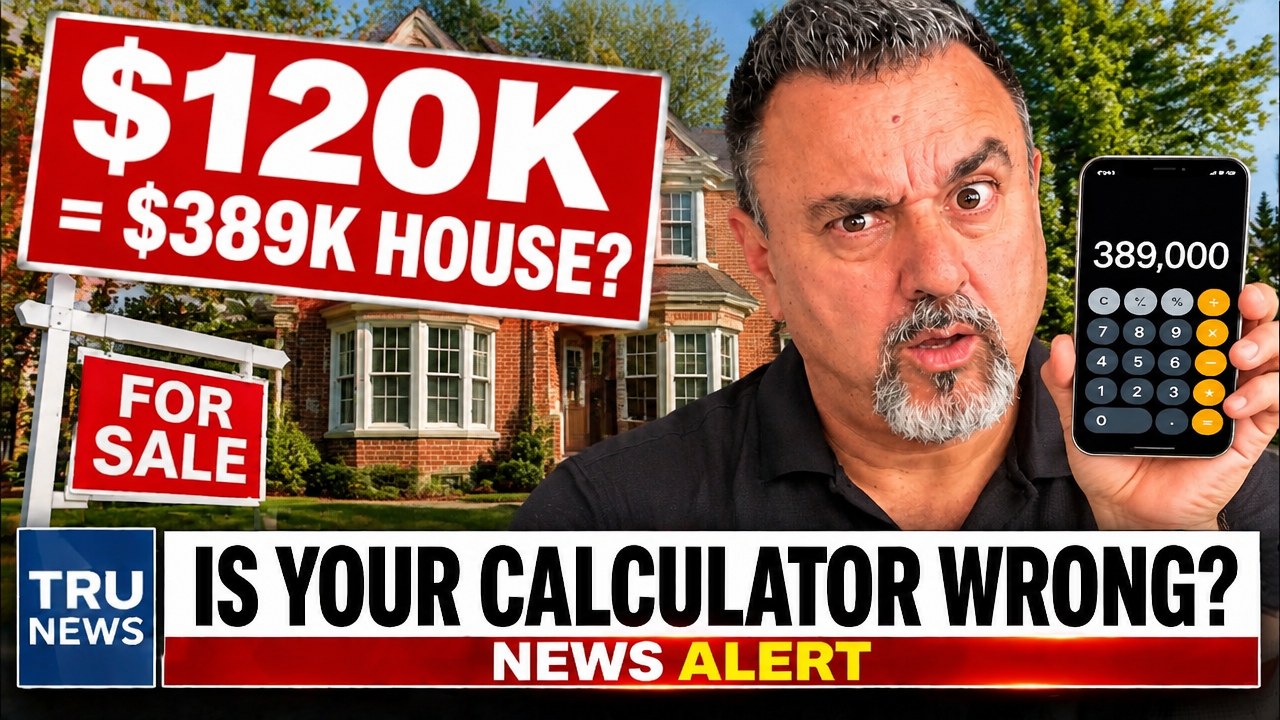
The buyer earns $120,000 a year, has about $750 a month in other debts, a 720 to 740 credit score and $15,000 to put down, buying in the 60623 ZIP code. Zillow's calculator, run on $100,000 of income, said about $274,000. Our lender math on the $120,000 buyer came out to about $357,000 on a conventional loan and about $389,000 with FHA, roughly $31,000 more house with the same income.
Cook County property taxes on this home were almost $7,000 a year, about $500 a month. That $500 counts against your payment just like principal and interest, so it can cost you tens of thousands of dollars in loan amount. Homeowners insurance and HOA dues work the same way, which is why a calculator that leaves them out can make you shop in the wrong price range.
FHA guidelines often allow a higher debt-to-income ratio than conventional, so the same buyer can qualify for more house. The trade-off is FHA mortgage insurance. The right program depends on your credit, down payment and how long you plan to keep the loan.
Want me to check your number? Book a free call. One application and one credit pull puts your file in front of 30+ lenders.
Examples are estimates for illustration only; your approval amount depends on credit, income, debts, property and program guidelines. Not a commitment to lend. Dan Frio | NMLS #246527 | PBT Bancorp | NMLS #257781 | Equal Housing Lender | 524 Main St, Hazard, KY 41701.