The Rate Update with Dan Frio · Tuesday, October 13, 2026
Mortgage Rates: Stocks Doubled—Why Are Home Buyers Still Priced Out?
Since October 12, 2022, we've lived through 8% mortgage rates, a tariff shock, and a war with Iran. None of it caused a crash. Now the Houthis are hitting Saudi Arabia again, oil is over $100, and rates are near two-year highs. Here's what it means for your payment.
+118%S&P 500 in 4 years
+13%Median home price
7.28%30-yr mortgage rate
+$390Monthly payment vs 2022
1🛢️ Houthis Strike Again: Oil, Inflation and Rates
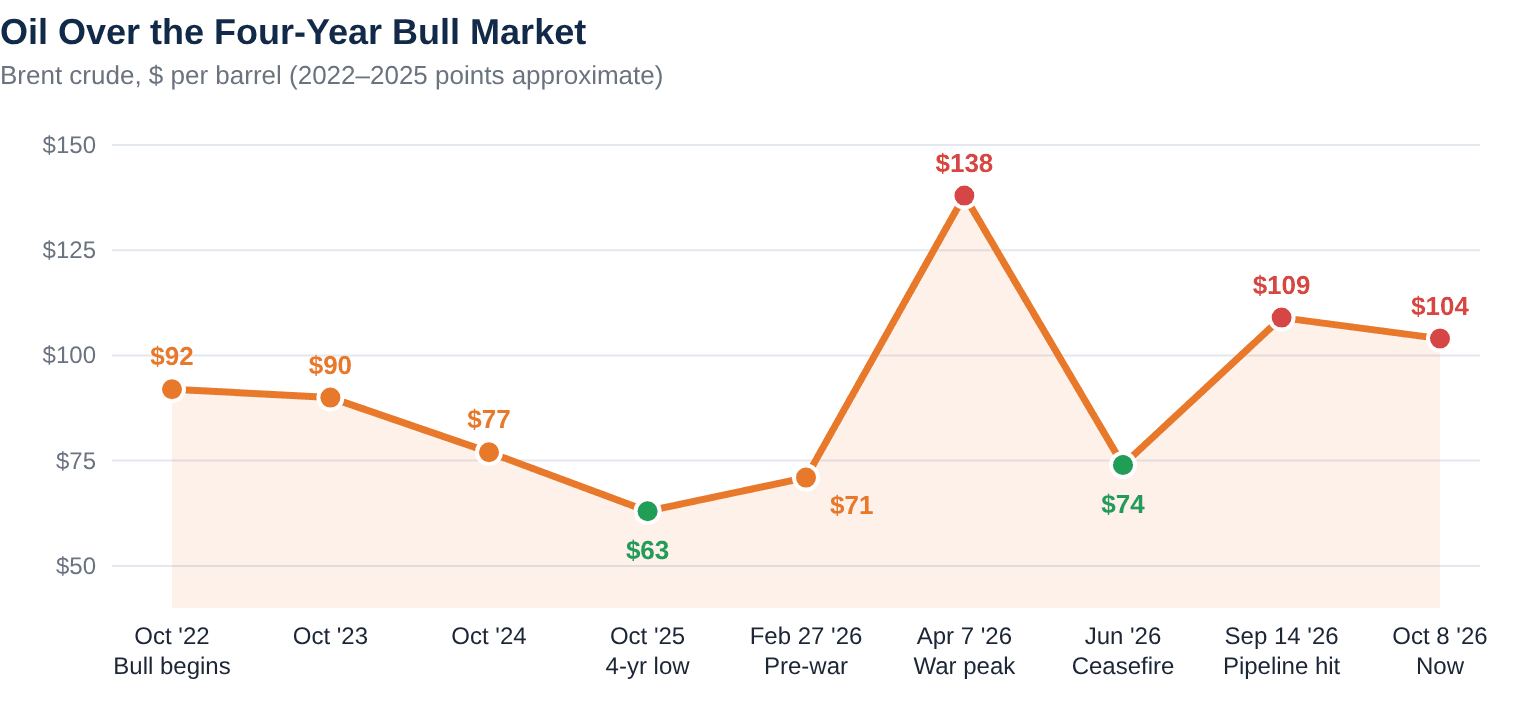
The Houthis keep hitting Saudi tankers and oil sites. With Hormuz largely shut, Saudi oil now goes out through the Red Sea, so two of the world's key oil routes are under pressure at once. Result: Brent back above $100 and the 10-year Treasury at 5.3%, the highest since 2002.
🛢️ Oil up→📈 Inflation up→🏦 Bond yields up→🏠 Mortgage rates up
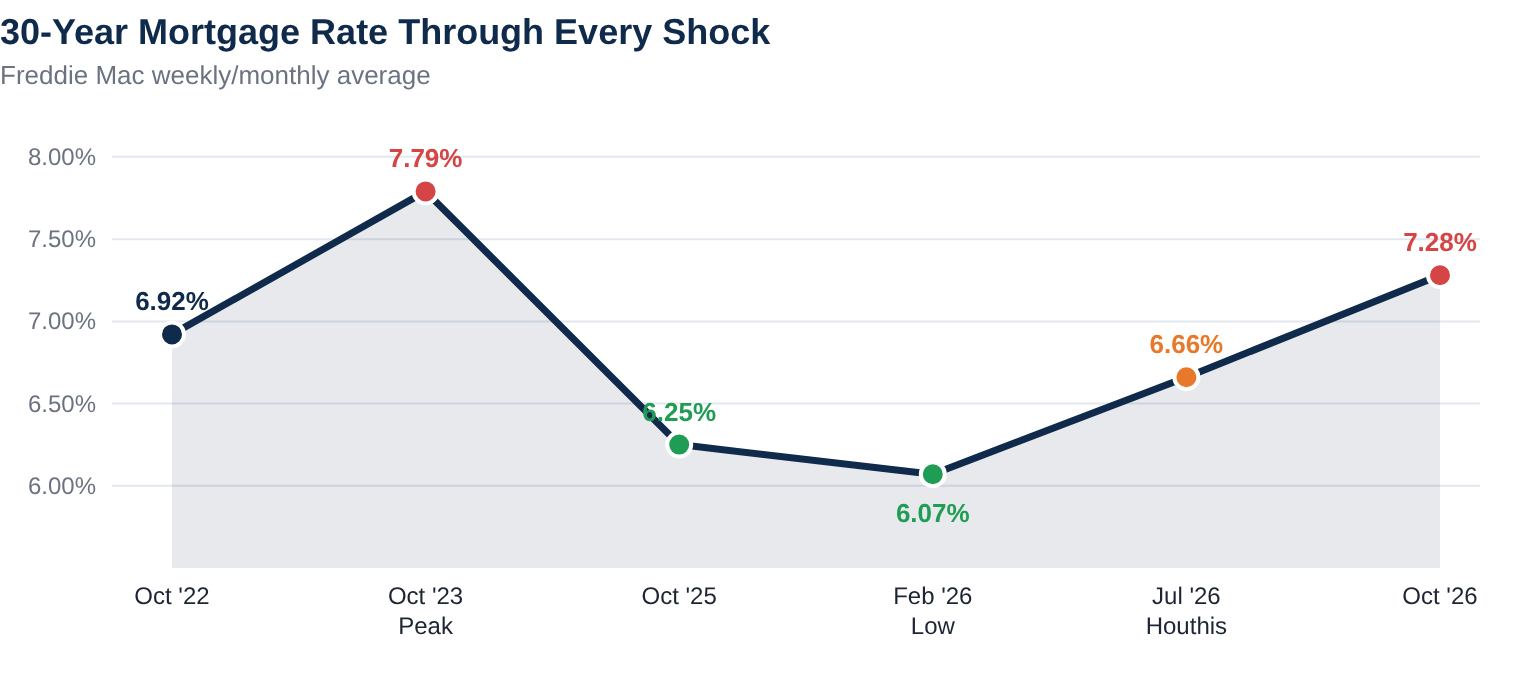
Bottom line: Oil went from $63 to $138 and back over $100, yet stocks kept rising. Your mortgage rate didn't get off so easy: 7.28% today vs. 6.34% a year ago.
↑ Back to top
2📈 Four Years of Stocks: Dow, S&P 500 and Nasdaq
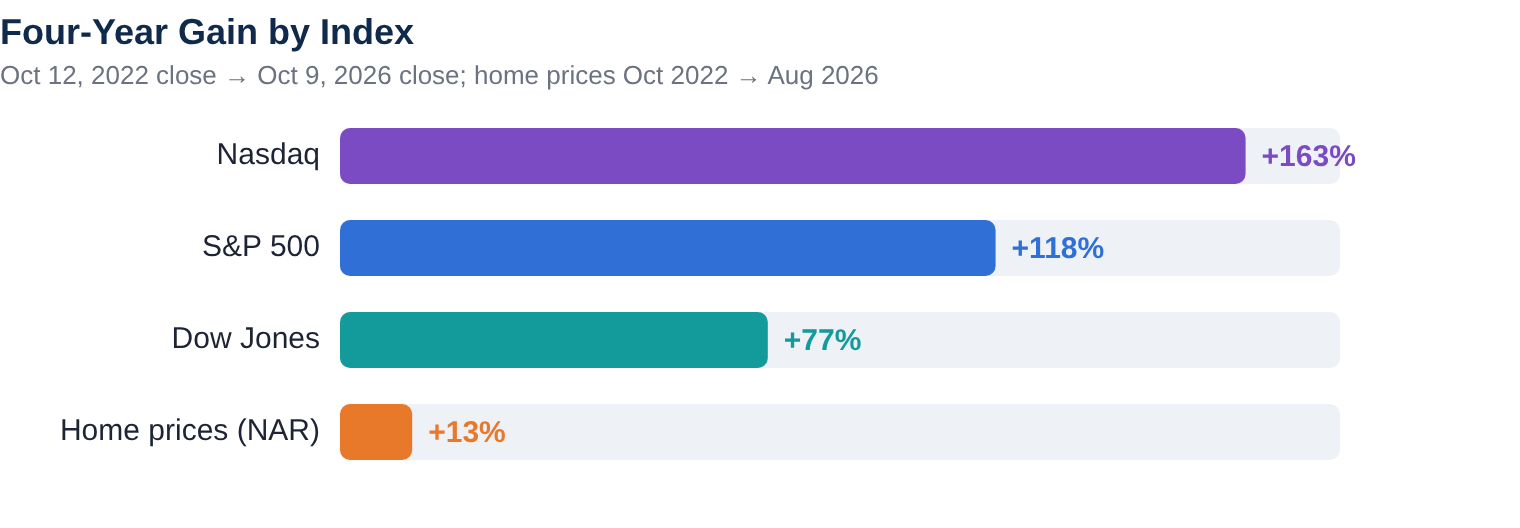
| Index | Close, Oct 12, 2022 | Close, Oct 9, 2026 | Gain |
|---|
| S&P 500 | 3,577 | 7,812 | +118% |
| Dow Jones | 29,211 | 51,655 | +77% |
| Nasdaq Composite | 10,417 | 27,366 | +163% |
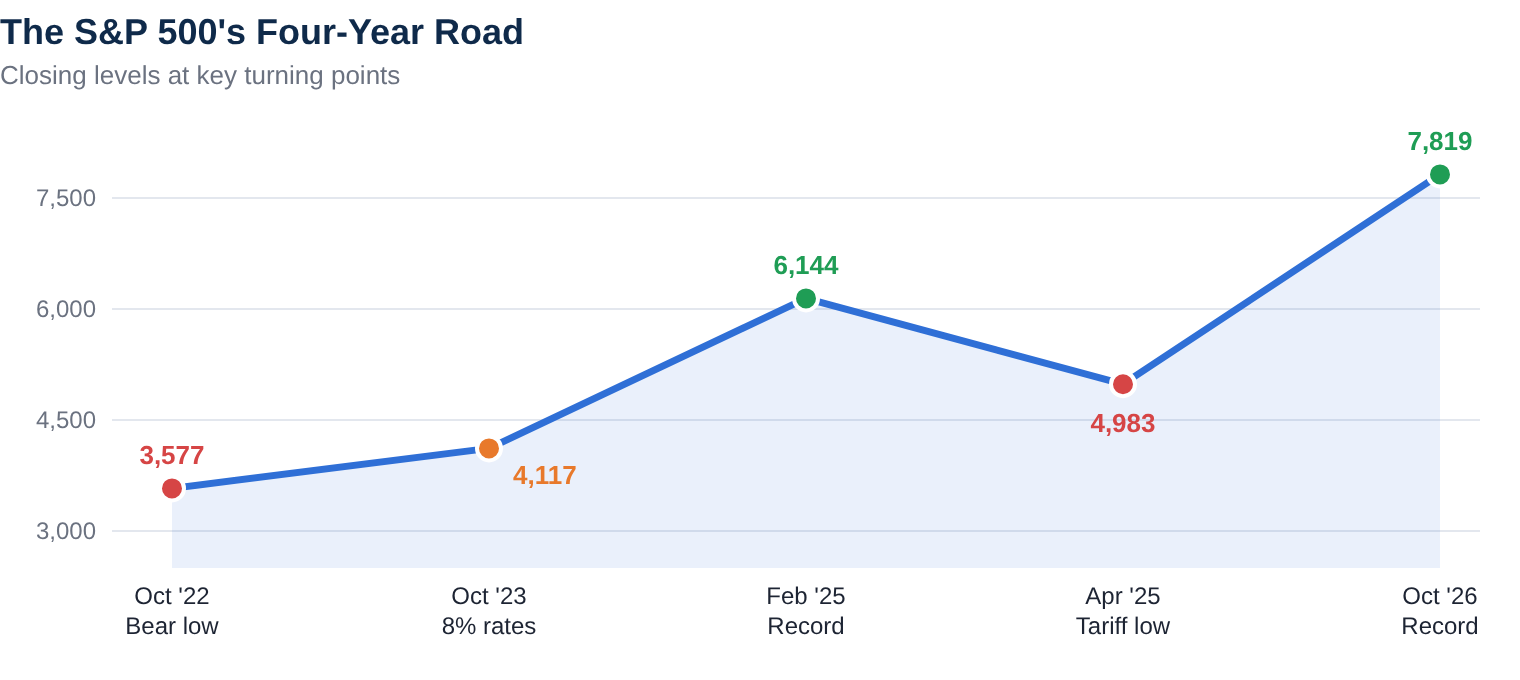
The S&P 500 set a record close of 7,818.93 on October 6 and is up about 14% this year alone, despite a war, $100 oil and a Fed rate hike. Much of the run has come from large technology and AI-related companies, which is why the Nasdaq leads.
History check: Every S&P 500 bull market since 1957 that reached its fourth birthday kept going. But in four of those six cases, the next bear market eventually dropped stocks below the fourth-birthday level. Valuations are also above their 10-year average.
↑ Back to top
3🏡 What Home Prices Did Over the Same Four Years
| Measure | October 2022 | Latest | Change |
|---|
| NAR median existing-home price | $379,100 | $429,100 (Aug 2026) | +13% |
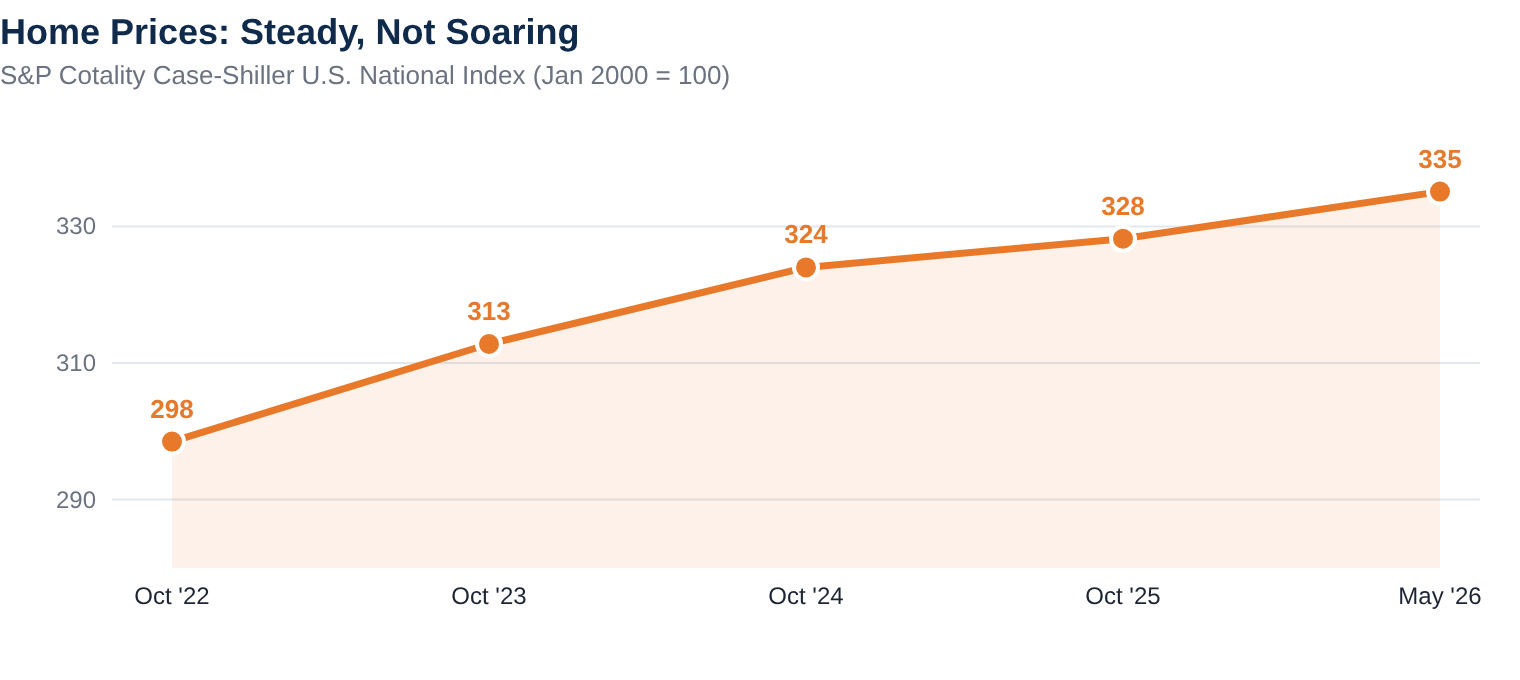
| Case-Shiller U.S. National Index | 298.5 | 335.1 (May 2026) | +12% |
| 30-year mortgage rate (Freddie Mac) | 6.92% | 7.28% (Oct 1, 2026) | Higher |
Stocks more than doubled. Home prices rose about 12–13%, roughly 3% a year and lately closer to 2%, which is below inflation. In real terms, home values have been flat to slightly down. August was the 38th straight month of year-over-year price gains, and inventory climbed to 1.62 million homes, the most since 2019.
The takeaway: Housing didn't crash and it didn't boom. It stalled. The pain has been in the monthly payment, not in collapsing prices.
↑ Back to top
4⚡ The Three Stress Tests That Didn't Break the Market
Home Buyers: Waiting for a Housing Crash That May Never Come?
2023Mortgage rates hit 8%Daily rates touched 8% in October and Freddie Mac's weekly average peaked at 7.79%, the highest since 2000. Sales slowed. Prices held, because owners with 3% loans didn't sell.
2025TariffsThe S&P 500 fell 18.9% from its Feb. 19 record to the April 8 close, just short of a bear market (intraday it crossed 20%). New highs followed within months.
2026The Iran warU.S. and Israeli strikes began Feb. 28. Hormuz traffic largely stopped in March and the Dow briefly erased its 2026 gains. Since July the Houthi blockade added a second front. Stocks still made records.
Why no crash? Corporate earnings kept growing, consumers kept spending, homeowners had low fixed-rate mortgages and real equity (unlike 2008), and lending standards stayed tight. Shocks raised costs, but they didn't force sales.
↑ Back to top
5💼 The Jobs Market: From Hot to Barely Growing
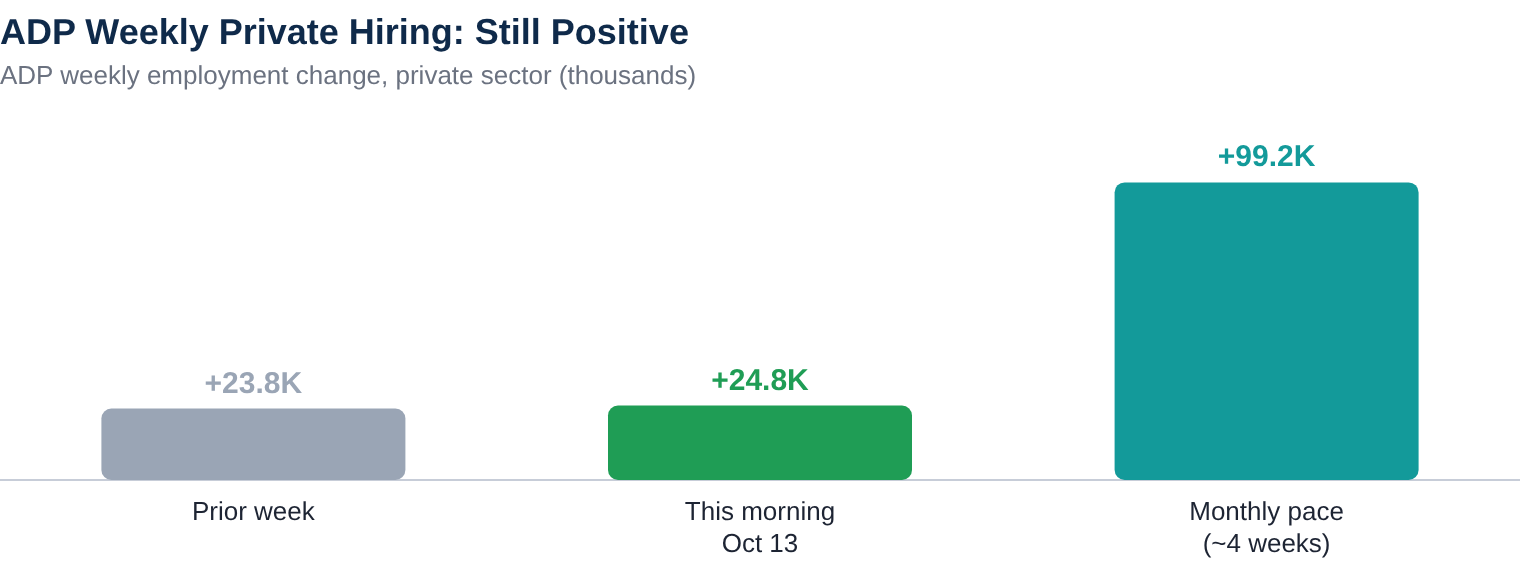
🆕 Just in this morning (8:15 a.m. ET): ADP reported private employers added about 24,800 jobs per week, up slightly from 23,800 the week before. That works out to roughly 100,000 jobs a month, a firmer pace than September's official count of just +46,000 private jobs. One data point doesn't reverse the trend, but it suggests hiring is slow, not stalling.
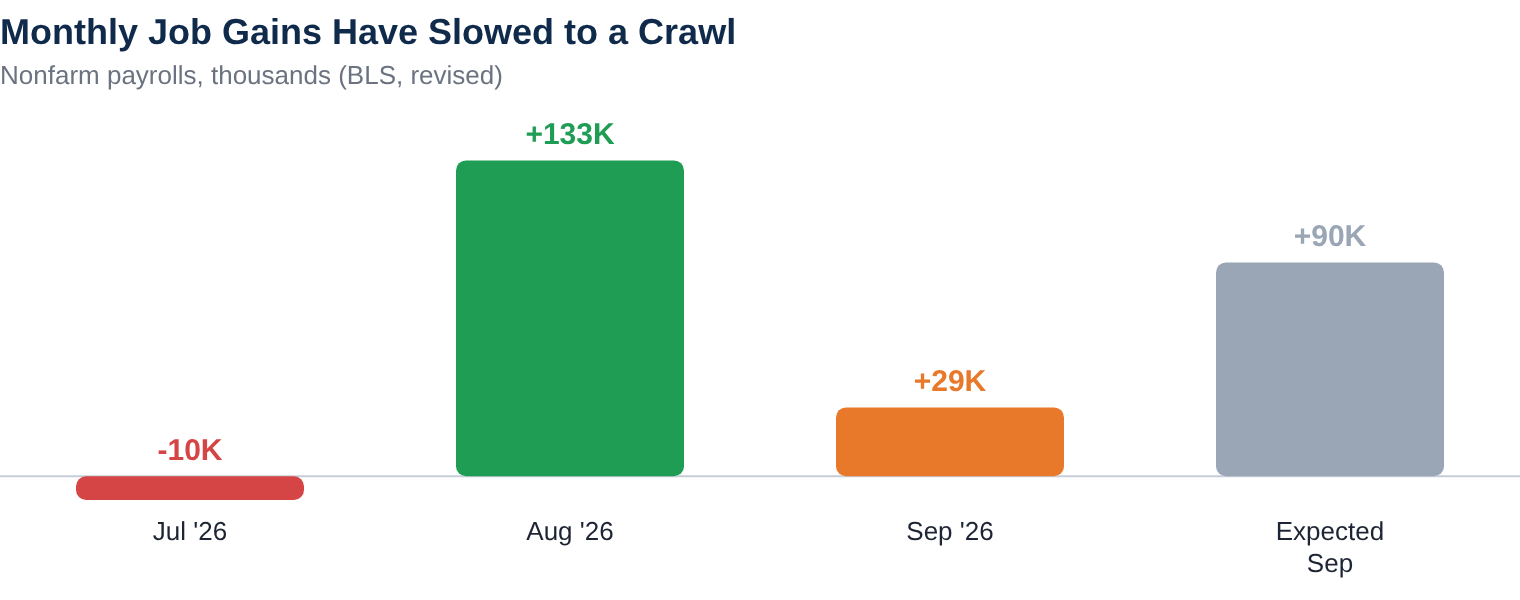
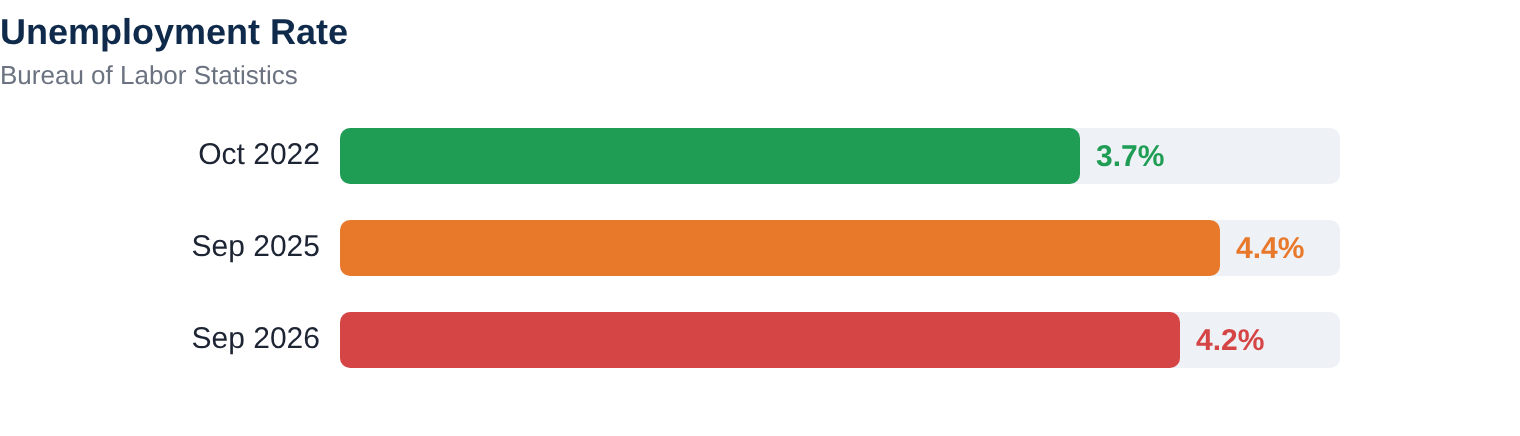
September's report was soft across the board: hiring missed badly, July and August were revised down by a combined 60,000 jobs, and wage growth slowed. The government's three-month average is now about 51,000 jobs a month, and unemployment has held in a narrow 4.1%–4.4% range since mid-2024.
The tug-of-war: A weak jobs report normally pushes mortgage rates down. This year, oil and inflation have been louder. Cooling jobs argue against more Fed hikes; expensive oil argues the other way. That's why rates have been so jumpy.
↑ Back to top
6💵 How This Affects Your Mortgage Payment
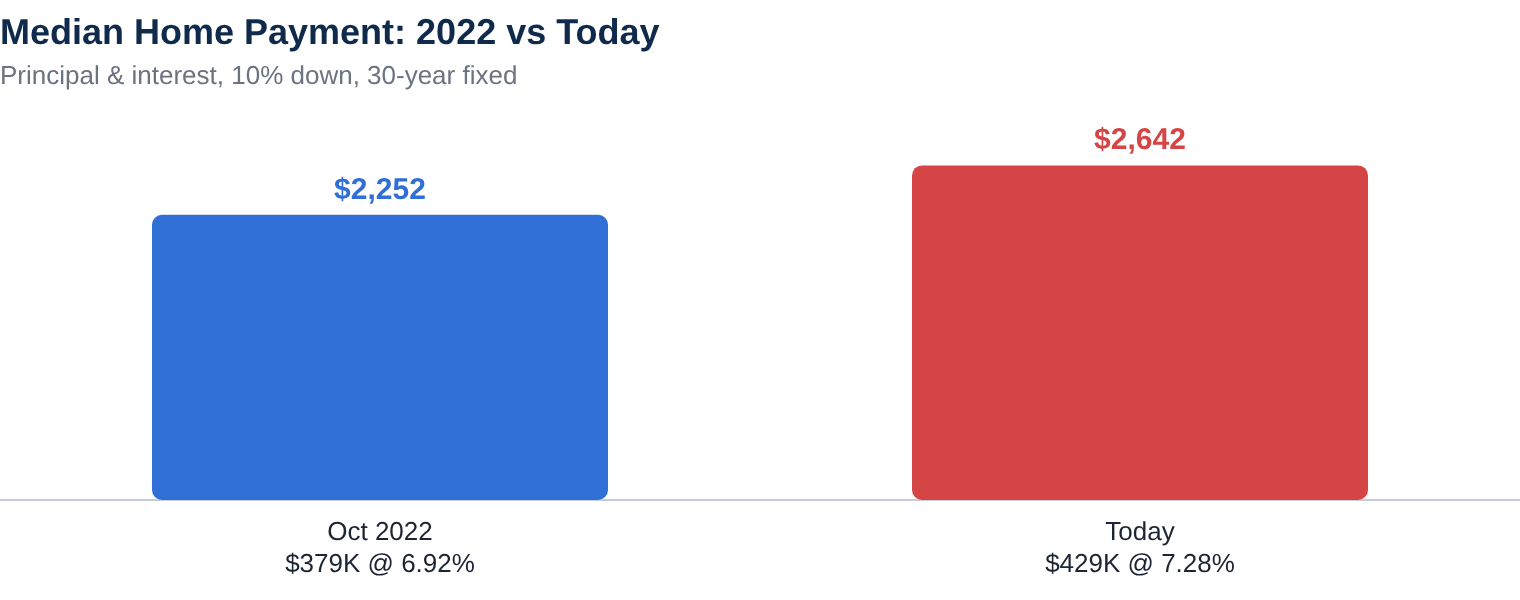
The median price is up 13%, but the payment is up about $390 a month (17%), and that's before property taxes and insurance, which have also risen.
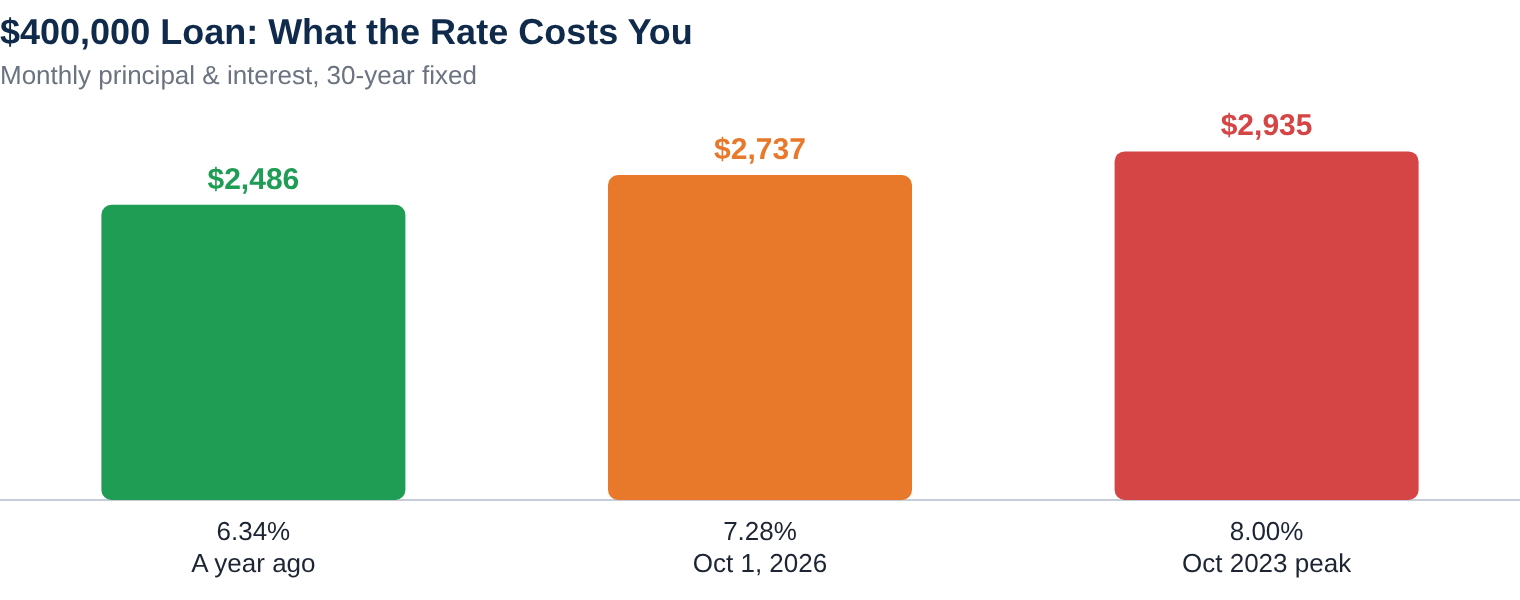
On a $400,000 loan, today's rate costs about $250 more a month than a year ago. Every quarter-point move is worth roughly $68 a month, or more than $24,000 over 30 years.
What you can do right now
🏠 Buying a Home
Today's 30-yr rate7.28%
Median home price$429,100
Homes for sale1.62M (most since 2019)
Payment, 10% down$2,642/mo
More inventory = more leverage. Ask for seller credits to buy down your rate, and compare 30+ lenders with one application and one credit pull.
Get Pre-Approved →🔄 Already Own
2023 peak rate7.79%
Rate today7.28%
Feb 2026 low6.07%
Each ¼ point on $400K≈ $68/mo
Locked in near 8%? Set a target rate and let me watch it. A move back toward the mid-6s could make a refinance worth running.
Set My Rate Alert →💵 Need Cash
Median home price, 2022$379,100
Median home price, now$429,100
Equity gained (median)+$50,000
Your first-mortgage rateKeep it
Don't give up a low rate for a cash-out refinance. A home equity line taps the equity and leaves your first mortgage alone.
See the 5-Day HELOC →✅ Everyone
Rate factor you controlCredit score
Value of ¼ point, $400K≈ $68/mo
Over 30 years$24,000+
Cost to checkFree
A higher score tier can be worth more than a quarter point. Know your score before a lender pulls it.
Check My Score ↓↑ Back to top
✅ What's Your VantageScore Credit Score?
Know your score before a lender pulls it. See where you stand, what's holding it back, and how much a higher score could save on your rate.
Get My FREE Credit Score →Sources: S&P 500 closes and bull-market history: Motley Fool via Webull (Oct 2026) and AP market closes (Oct 9, 2026). Home prices: National Association of Realtors existing-home sales (Aug 2026); S&P Cotality Case-Shiller U.S. National Index via FRED. Mortgage rates: Freddie Mac Primary Mortgage Market Survey. Jobs: Bureau of Labor Statistics, Employment Situation, September 2026. Oil and Houthi coverage: Reuters, Al-Monitor, Oilprice.com, Business Standard. Payment examples are principal and interest only, 30-year fixed, and exclude taxes, insurance and mortgage insurance.
Dan Frio | NMLS #246527 | PBT Bancorp | NMLS #257781 | Equal Housing Lender | 524 Main St, Hazard, KY 41701
Dan Frio is a federally registered mortgage loan officer with PBT Bancorp. Mortgage assistance is available in the states and jurisdictions served by the bank. Mortgage products are originated by PBT Bancorp, NMLS #257781. Rates and payments shown are examples for illustration only, are not a commitment to lend, and are subject to change and credit approval. This article is for educational purposes and is not investment advice.