2014 / MORTGAGE SECURITIES
$16.65B settlementFinancial-crisis mortgage and securities claims.
Included a $5B civil penalty and $7B consumer relief.[6]
FinCEN / OCC + OFAC
Not reported on time
National security & other risks
Treasury says Bank of America failed to timely report more than $5 billion in suspicious activity and maintained ineffective safeguards against illicit finance. The bank admitted willful Bank Secrecy Act violations in a civil resolution.[1]
Regulators say warning signs persisted—and significant failures continued after a December 2024 order.[1]
The sanctions case is separate from the $5B reporting finding. Suspicious transaction volume is not bank profit. OFAC classified its violations as non-egregious.
The bank says it has invested billions in technology and thousands of employees in financial-crime compliance and is completing remediation.[14]
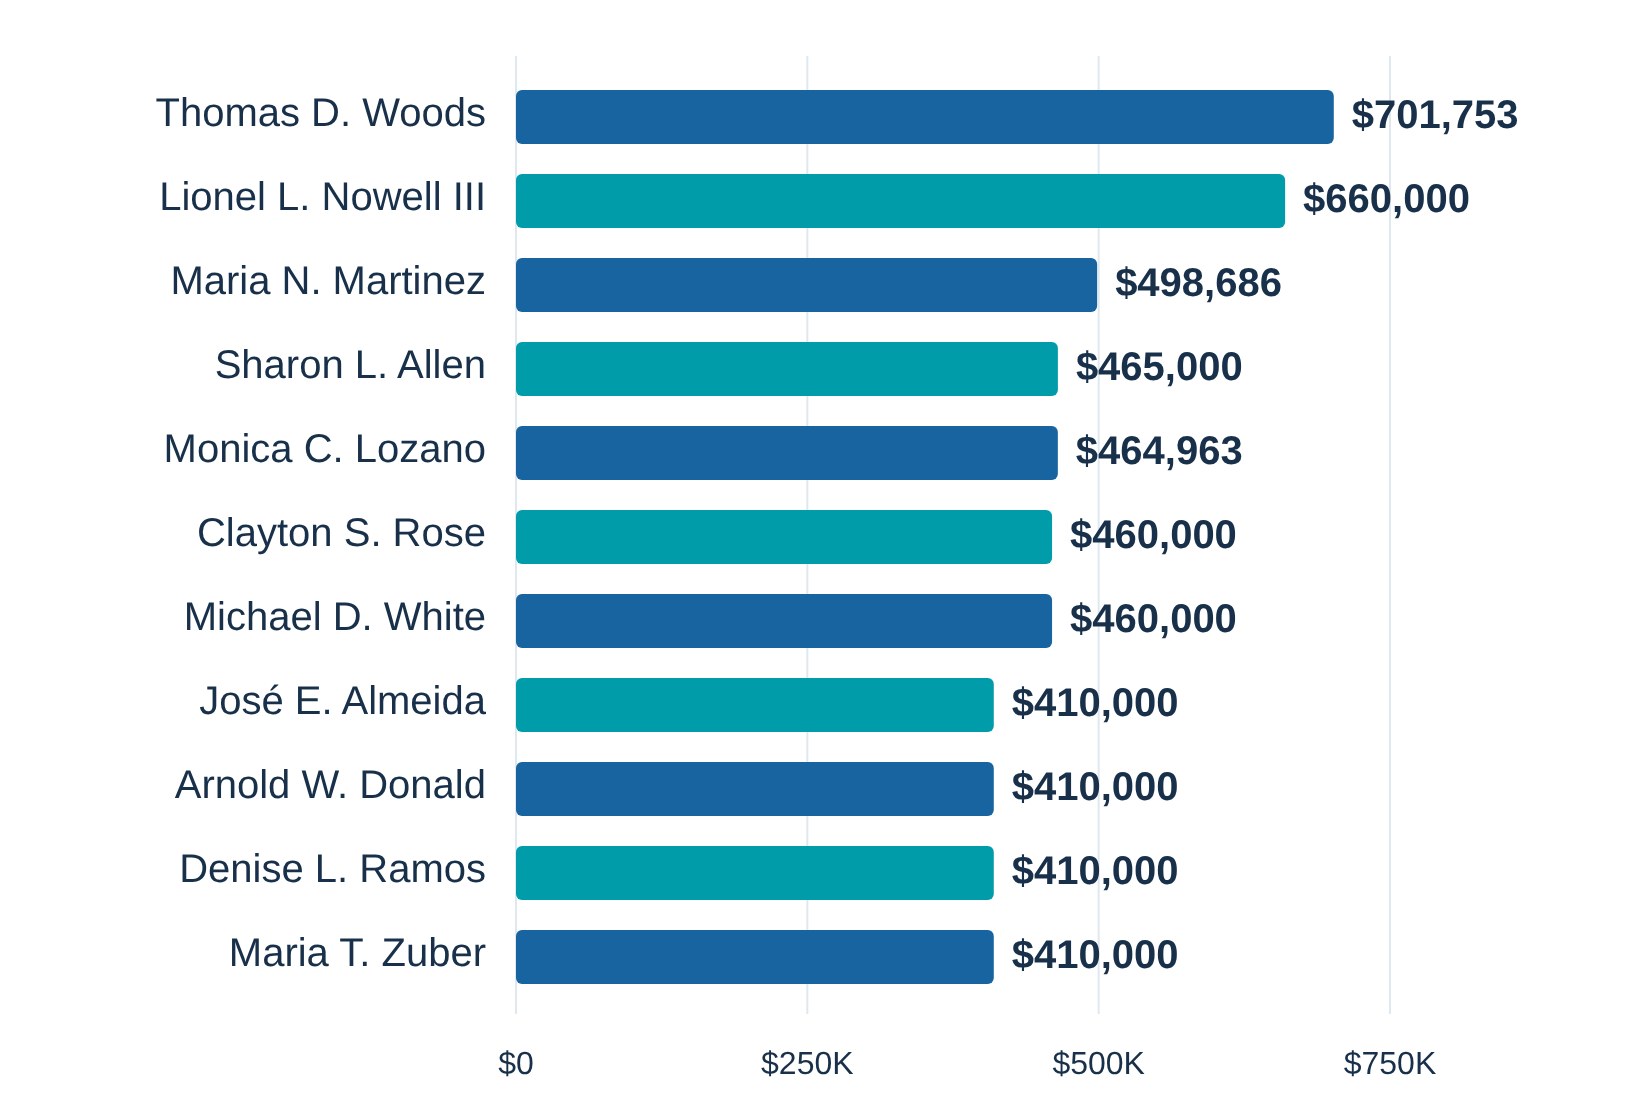
Awarded pay, not cash received. SEC summary-table compensation: $33,711,521 under different timing/valuation rules. No separate board fee.[4]
Lionel Nowell: lead independent director.
Sharon Allen: audit chair.
Monica Lozano: compensation chair.[5]
Combined 2025 compensation for the 11 currently listed non-management directors. Corporate board shown; the enforcement respondent is Bank of America, N.A.
Not a flat percentage. FinCEN assessed $1.2B after weighing violations, harm, financial benefit and other enforcement factors.[2]
OFAC’s separate $11.66M: schedule amounts for 413 undisclosed violations, plus half the transaction values of 62 voluntarily disclosed violations.[3]
The public FinCEN order does not provide a complete count × rate worksheet. The $750M OCC payment is credited against the $1.2B assessment.
The penalty equals 3.97% of Bank of America’s 2025 companywide net income—or roughly 15 days at that year’s average profit pace.
FinCEN says the bank likely saved hundreds of millions in compliance costs and retained high-risk, high-value customers despite compliance recommendations.[2]
Scale comparison only: $1.2117B ÷ $30.5B. Different periods; total company profit is not profit from the violations. Remediation and other costs are excluded.[4]
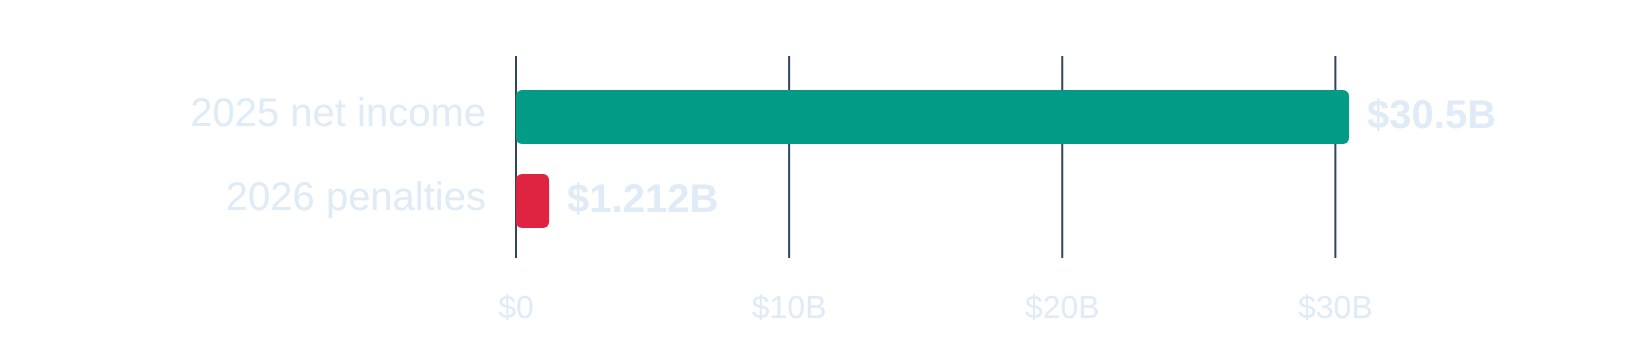
Linear scale · billions of dollars · 2025 net income vs. October 2026 penalties.
If the financial benefits exceed the consequences,
what stops the cycle from repeating?
Hypothetical incentive cycle, not a finding that Bank of America earned billions from laundering. The affected-business profit has not been quantified in the reviewed public record.
Editorial analysis. A corporate penalty does not automatically remove the CEO or board, and the reviewed announcements do not announce their removal.
Consumer relief excluded from bars · millions / billions of dollars
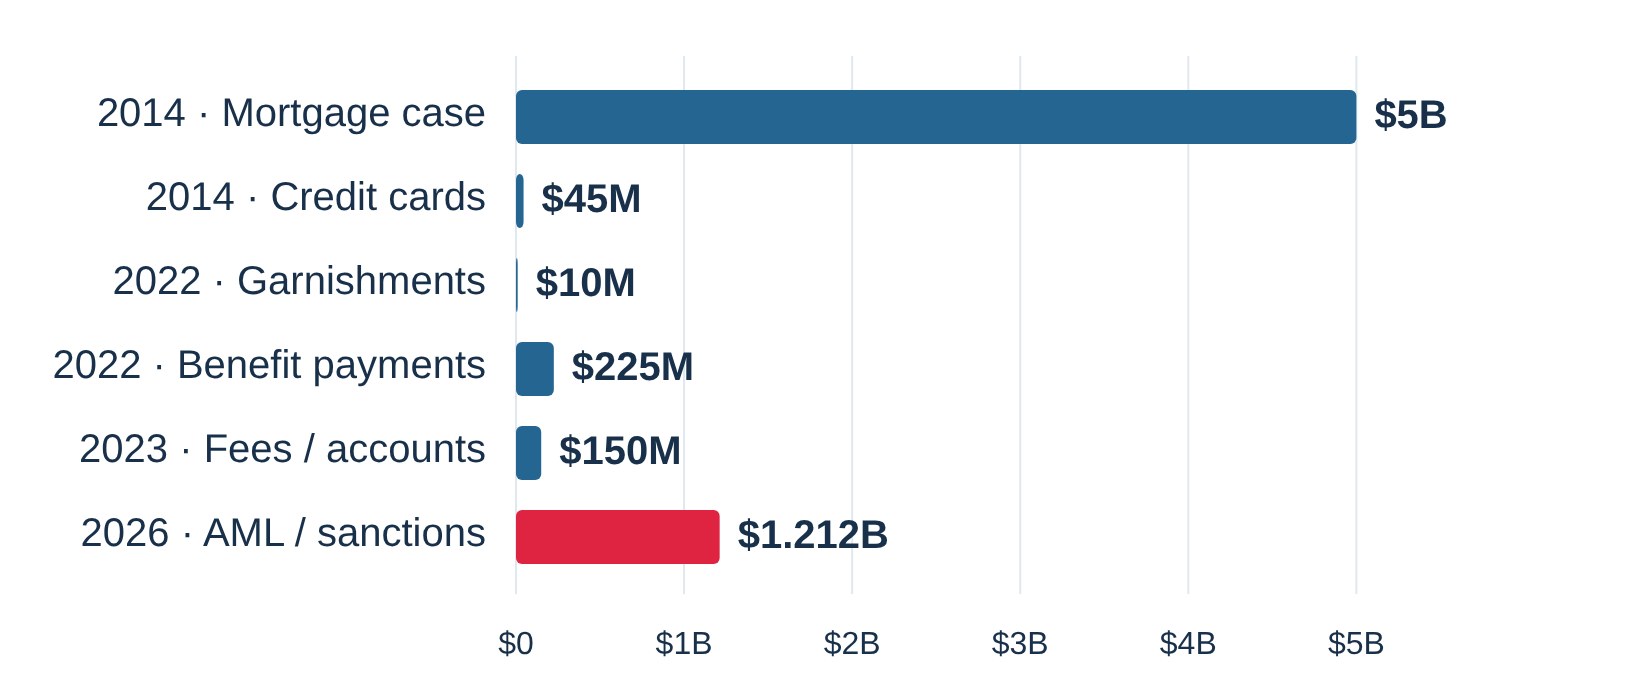
Financial-crisis mortgage and securities claims.
Included a $5B civil penalty and $7B consumer relief.[6]Deceptive marketing and unfair billing.
$20M CFPB + $25M OCC; $727M consumer relief separately.[7]Unlawful account garnishments.
Separate CFPB action in May 2022.[8]Faulty fraud filters and frozen benefits.
$100M CFPB + $125M OCC; consumer redress separately.[8]Repeat fees, withheld rewards, unauthorized accounts.
$90M CFPB + $60M OCC; over $100M consumer compensation.[9]The current breaking-news enforcement action.
Separate findings from the earlier consumer and mortgage cases.[1]Selected cases, not a complete lifetime total. Different conduct and remedies; the $16.65B settlement is not plotted as though every dollar was a fine.
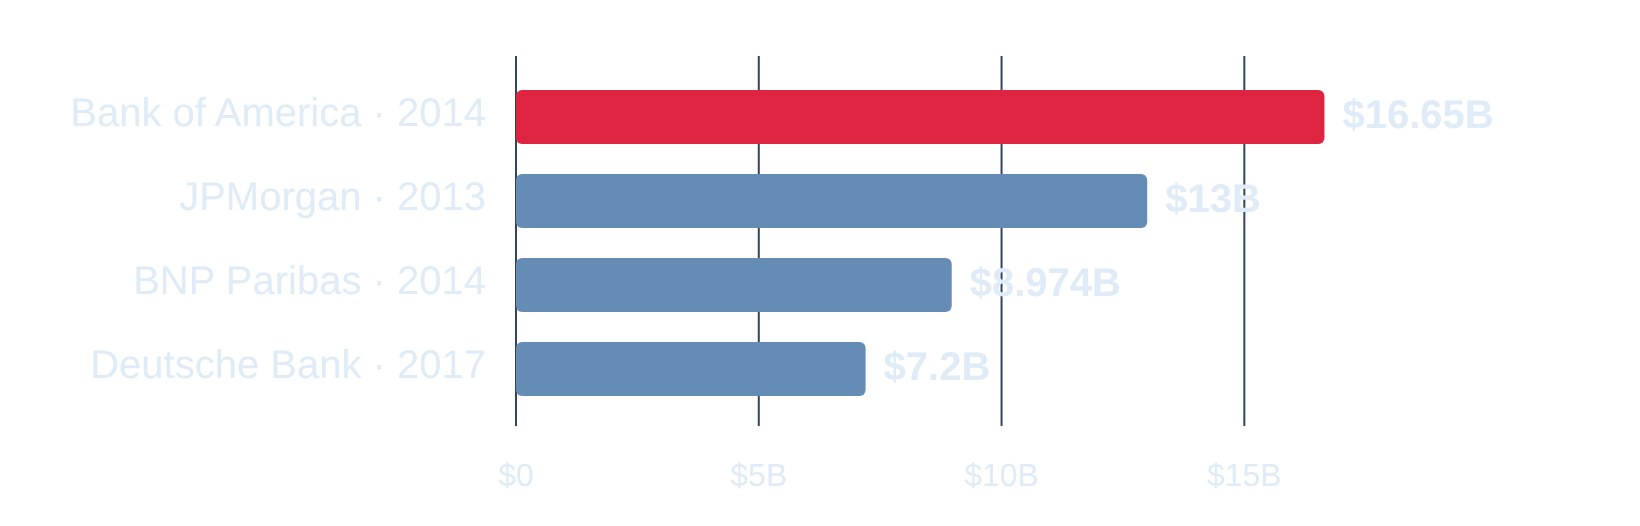
Selected historical examples, not a complete worldwide ranking. Totals include claims settlements, consumer relief or forfeitures; they are broader than fines alone.[6][10][11][12]
Bank of America reported third-quarter results this morning with the penalty booked. Earnings came in at $0.91 a share against roughly $1.09 expected. Excluding the fine, adjusted earnings were $1.08. Revenue was $30.0 billion against about $30.55 billion expected.[18]
The penalty is not tax-deductible. Shares were down about 4% before the opening bell.[18]
Early-morning figures as of October 14.
| Measure | Actual | Economists | TRU forecast | Closer call |
|---|---|---|---|---|
| Headline CPI, month | +0.6% | +0.6% | +0.54% (rounds to 0.5%) | Economists |
| Core CPI, month | +0.3% | +0.2% | +0.26% (rounds to 0.3%) | TRU ✓ |
| Headline CPI, year | 3.7% | 3.6–3.7% | ≈3.6% | Economists (Reuters 3.7%) |
| Core CPI, year | 2.6% | 2.5% | ≈2.5% | Both 0.1 low |
Economist estimates from the Reuters and Wall Street Journal polls published October 12; Barron's had 3.6% headline annual. TRU figures from our final forecast published October 12.[17]
| Month | Headline actual | Economists | TRU | Core actual | Economists | TRU |
|---|---|---|---|---|---|---|
| July | +0.1% | +0.1% | — | +0.2% | +0.3% | — |
| August | +0.4% | +0.4% | +0.41% | +0.3% | +0.2% | +0.26% ✓ |
| September | +0.6% | +0.6% | +0.54% | +0.3% | +0.2% | +0.26% ✓ |
| 3-month average | +0.37% | +0.37% | +0.48%* (actual +0.50%) | +0.27% | +0.23% | +0.26%* (actual +0.30%) |
| Month | Headline annual | Economists | TRU | Core annual | Economists | TRU |
|---|---|---|---|---|---|---|
| July | 3.4% | 3.4% | — | 2.5% | 2.5% | — |
| August | 3.4% | 3.4% | 3.4% | 2.4% | 2.4% | 2.4% |
| September | 3.7% | 3.6–3.7% | ≈3.6% | 2.6% | 2.5% | ≈2.5% |
Monthly readings seasonally adjusted; annual readings unadjusted. *TRU averages cover August–September; our published forecast series began with August. July consensus per Kiplinger; other July surveys had core at +0.2%. August consensus per Nowflation's forecaster grading.[13][15][16]
The 12-month rate is 2.6% for core, but the last three months are running at about 3.2% annualized. That is the number the bond market watches, and it is moving the wrong way for mortgage rates.
Gasoline +9.1% after seasonal adjustment, more than half of the monthly increase. Raw pump prices rose 6.5%; the seasonal factor pushed it higher, as our forecast warned. Energy is up 20.4% over the year.
Shelter +0.4%, up from 0.3% in August. Owners' equivalent rent rose 0.3% and hotel rates jumped 2.0%.
Airfares +1.2% on the month and +22.4% over the year. Used cars +0.7%. Food was unchanged.
Gasoline: we had +7.5%, actual +9.1%.
Shelter: we had +0.25%, actual +0.4%.
Used cars: we had −0.2%, actual +0.7%.
Offset: food came in at 0.0% vs. our +0.2%.
Lesson for October: the seasonal factor amplified the gas spike more than we assumed, and the wholesale used-car decline has not reached retail prices yet.
This is the "hot headline, core 0.3%" row on our Wednesday cheat sheet: short-term pressure on the 10-year Treasury, which closed at 5.24% on Friday, and limited relief for mortgage rates. The offset is that pump prices have been falling in October, so next month's headline should cool. Core is the problem. It has now run 0.3% two months in a row.
Educational information, not a commitment to lend or a rate guarantee. Monthly readings seasonally adjusted; annual readings unadjusted.[13]
The Producer Price Index measures what businesses receive for their goods and services. Higher diesel and jet fuel feed straight into producer energy and freight costs.
The wildcard is trade margins: when retailers absorb part of a fuel spike, their margins shrink and pull the headline number down. That is why our forecast is not higher.
Headline near 0.5% with core near 0.3% confirms the CPI story.
Headline 0.8% or core 0.5% means inflation is spreading through the supply chain, and more pressure on mortgage rates.
| PPI measure | August actual | Economists | TRU forecast |
|---|---|---|---|
| Headline PPI, month | +0.4% | +0.5% | +0.51% |
| Core PPI (ex food & energy), month | +0.2% | +0.3% | — |
| PPI ex food, energy & trade, month | +0.3% | Not published | +0.28% |
| Headline PPI, year | 5.4% | Not verified | ≈5.3% |
| PPI ex food, energy & trade, year | 4.7% | Not verified | ≈4.8% |
TRU annual figures are base-effect approximations. Wall Street's core PPI excludes food and energy; ours also excludes trade services, so the two are different measures.[17]
I spoke with Moira Ritter of Homes.com News for her Oct. 12 article, Mortgage rates top 7%: Why more borrowers are turning to ARMs and buydowns.[19] With the 30-year fixed at 7.4%, its highest weekly average since November 2023, lenders are offering alternatives: adjustable-rate mortgages, temporary rate buydowns and interest-only loans.
My preferred alternative right now is a temporary rate buydown, usually paid by the seller as a concession at closing. The money sits in escrow and lowers your payment for the first years. If you sell or refinance early, the remaining funds can be used to buy your rate down permanently.
| Year | Your rate | Monthly P&I | Monthly savings |
|---|---|---|---|
| Year 1 | 5.40% | $2,246 | $523 |
| Year 2 | 6.40% | $2,502 | $267 |
| Year 3+ | 7.40% | $2,770 | — |
Illustration only; principal and interest. Total subsidy ≈ $9,490, typically funded by a seller concession. Program rules and limits vary by loan type.
Want to know what this week's inflation reports mean for your loan, or whether a seller-paid buydown makes sense for you? Already have a Loan Estimate? I'll review it free and compare it across 30+ lenders.
Get a free Loan Estimate review →· Call or text (630) 360-3490
Research cut-off: October 13, 2026; CPI and earnings updated October 14. Charts use exact sourced amounts, linear scales and labeled periods. Leadership pay is latest disclosed 2025 compensation. Generated hero imagery is illustrative.