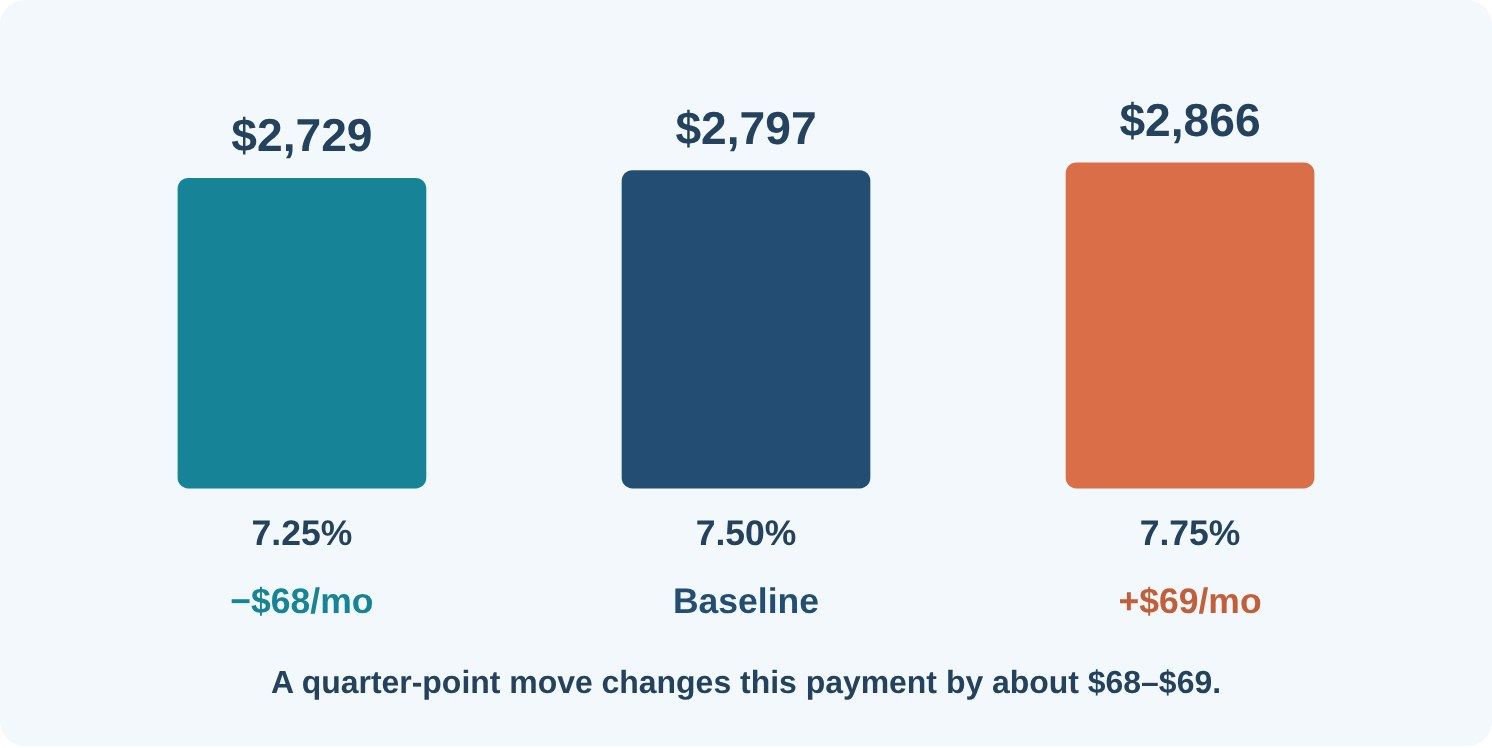
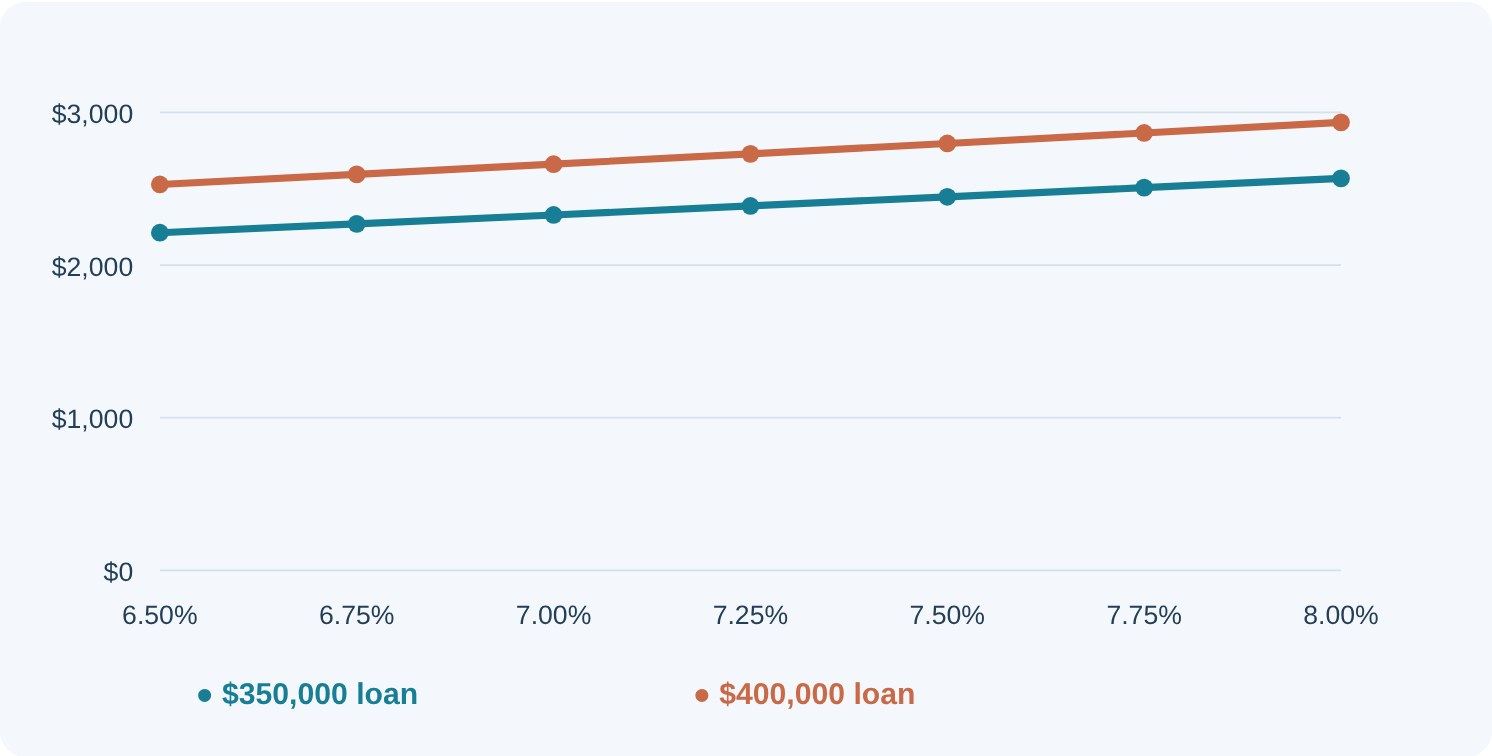
Brent oil hit a five-month high near $112, yet mortgage bonds improved. Here is why softer hiring may be outweighing oil, what the Fed is watching before its October 28 decision, what a quarter-point move costs on a $400,000 loan, and how to decide whether to lock or float.
THE RATE UPDATE WITH DAN FRIO
October 20, 2026 • Morning market briefing
Oil Up. Bonds Up. What About Your Rate?
The numbers homebuyers and Realtors need today.
The Rate Update with Dan Frio · NMLS #246527
BRENT INTRADAY HIGH$111.75Reuters report • five-month high
BRENT MORNING MOVE+1.1%Snapshot supplied for the show
BRENT HIGH5 MONTHSReported October 20
TAKEAWAY A supply scare can pressure rates. The economy’s response also matters.
Oil figures refer to different intraday snapshots. Reported attacks and unverified claims should remain attributed. [1]
02 • WHY THE RALLY?
The Fed’s two mandates.
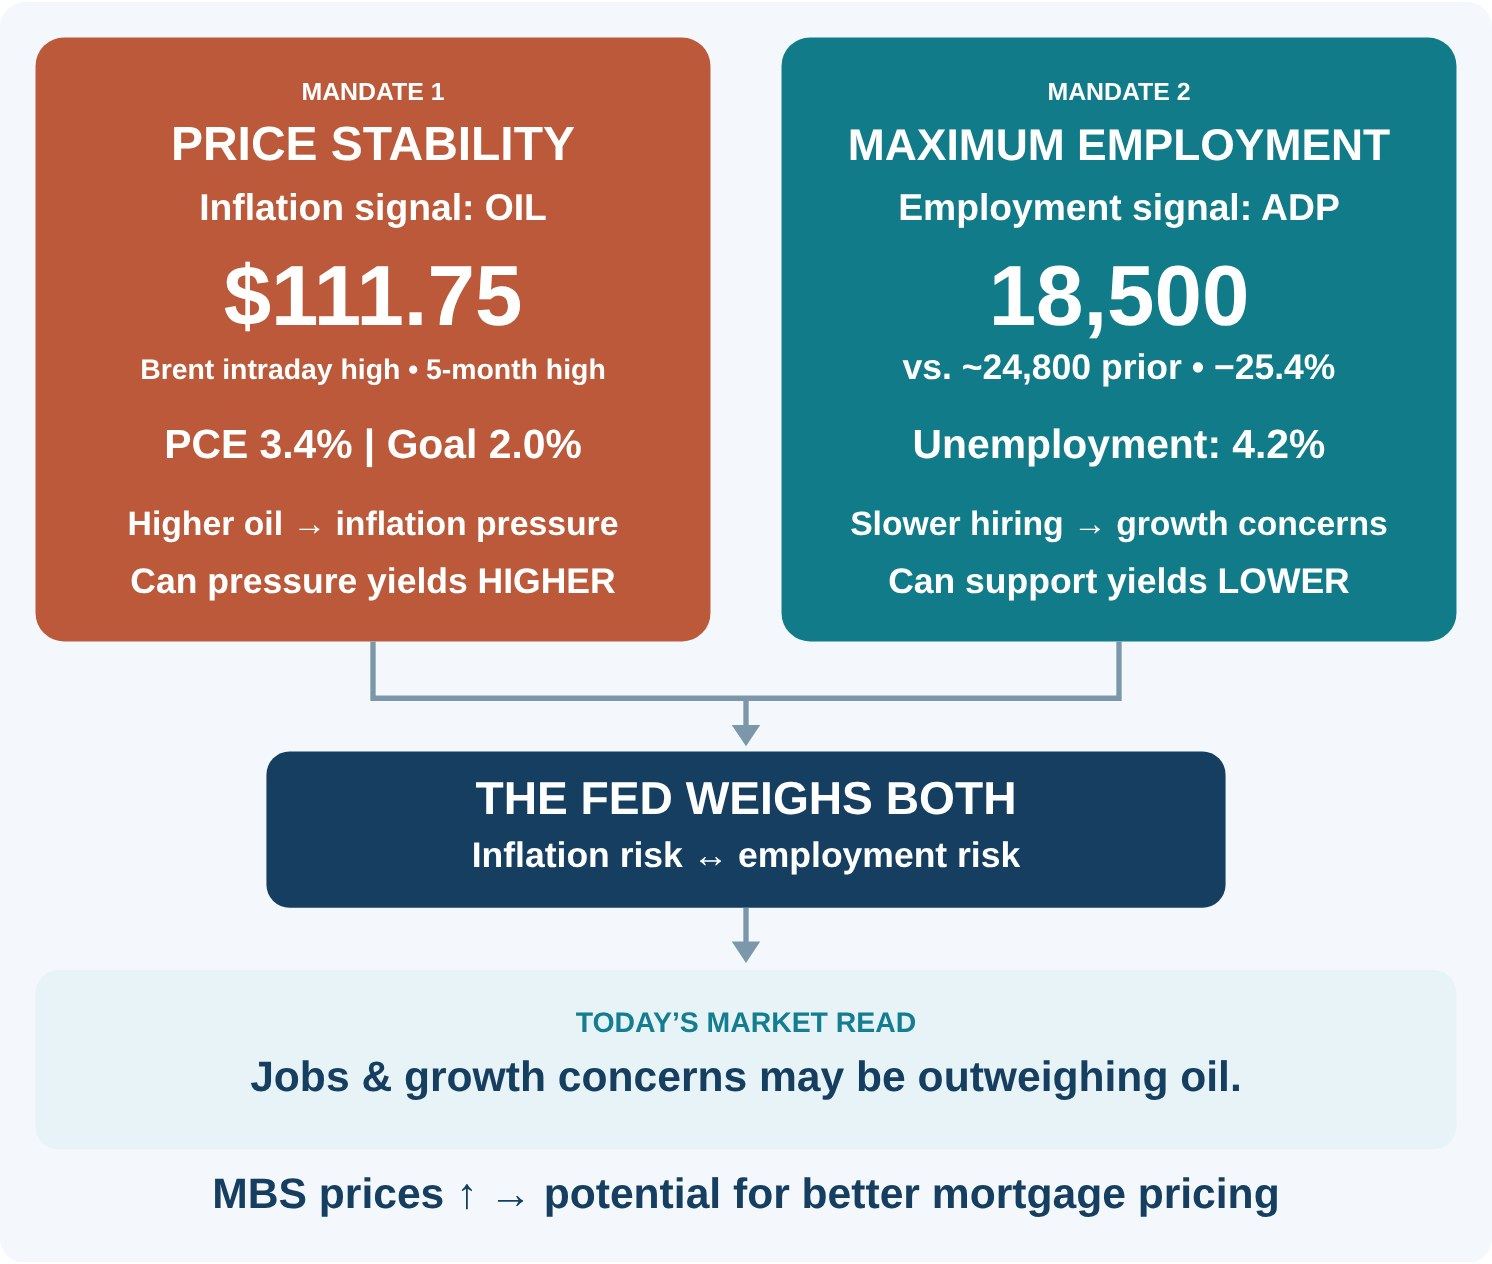
THE FED’S DUAL MANDATE • TODAY’S TUG-OF-WAR
Inflation (Oil) vs. Employment (ADP)
Two mandates. Two competing signals. One policy decision.
Price stability and maximum employment are the mandates; oil and ADP are signals. Brent: Reuters intraday report. PCE: August, BEA. Unemployment: September, BLS. ADP comparison: Dan’s screen, awaiting primary-source confirmation. The Fed does not have a fixed unemployment target. Market interpretation does not establish the cause of today’s rally.
“Oil pressures the inflation mandate. Softer ADP raises employment concerns. Today, bonds appear more focused on jobs and growth.”
Possible contributors, not proven causes. Treasury buying does not establish direct flows into MBS. [9]
03 • JOBS
Still hiring. Slower pace.
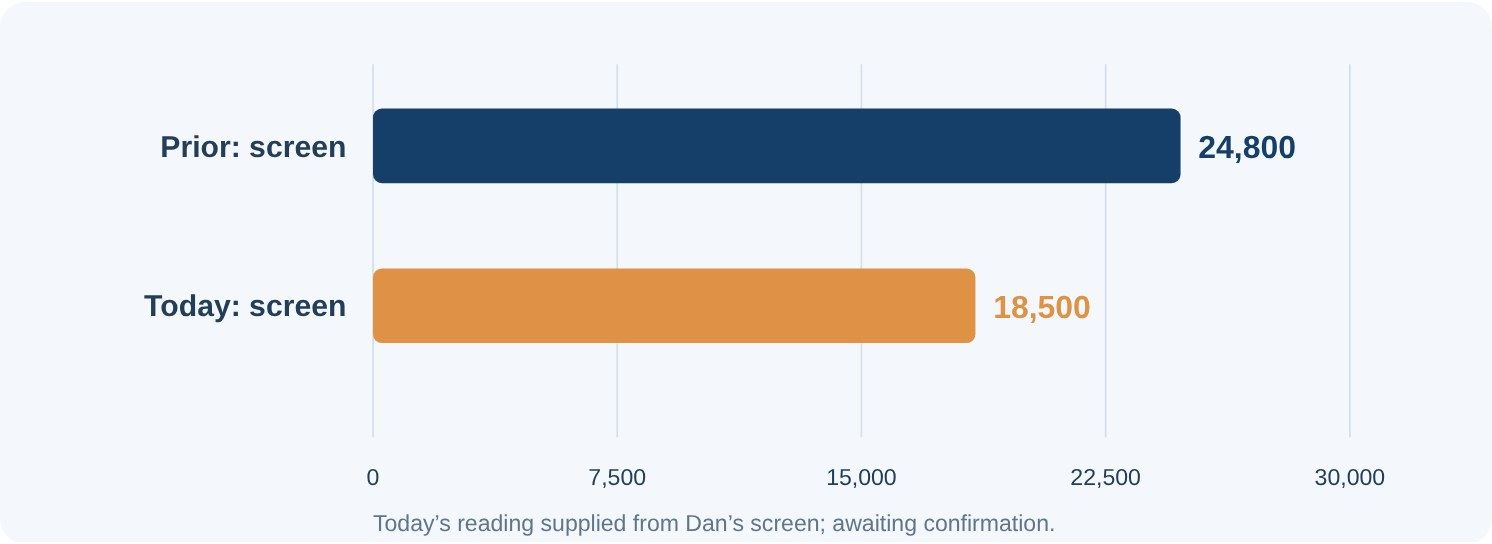
PRIOR: SCREEN24,800Approximate reading
CURRENT: SCREEN18,500Four-week moving average
CHANGE−25.4%−6,300 average weekly gains
THE RATE UPDATE • VISUAL EXPLAINER
A slower pace of hiring—not job losses
Average weekly private-sector job gains; four-week moving average.
Screen readings supplied by Dan: prior approximately 24,800; current 18,500. The October 13 ADP release reported 24,750 before any subsequent revisions. Current figures await primary-source confirmation. This is not a monthly payroll total.
TAKEAWAY Positive job growth. A softer pace. One reading does not establish a recession.
Both comparison figures supplied by Dan. ADP’s October 13 release showed 24,750 before subsequent revisions; today’s release has not been independently confirmed. [2]
04 • FED DASHBOARD
Inflation vs. employment.
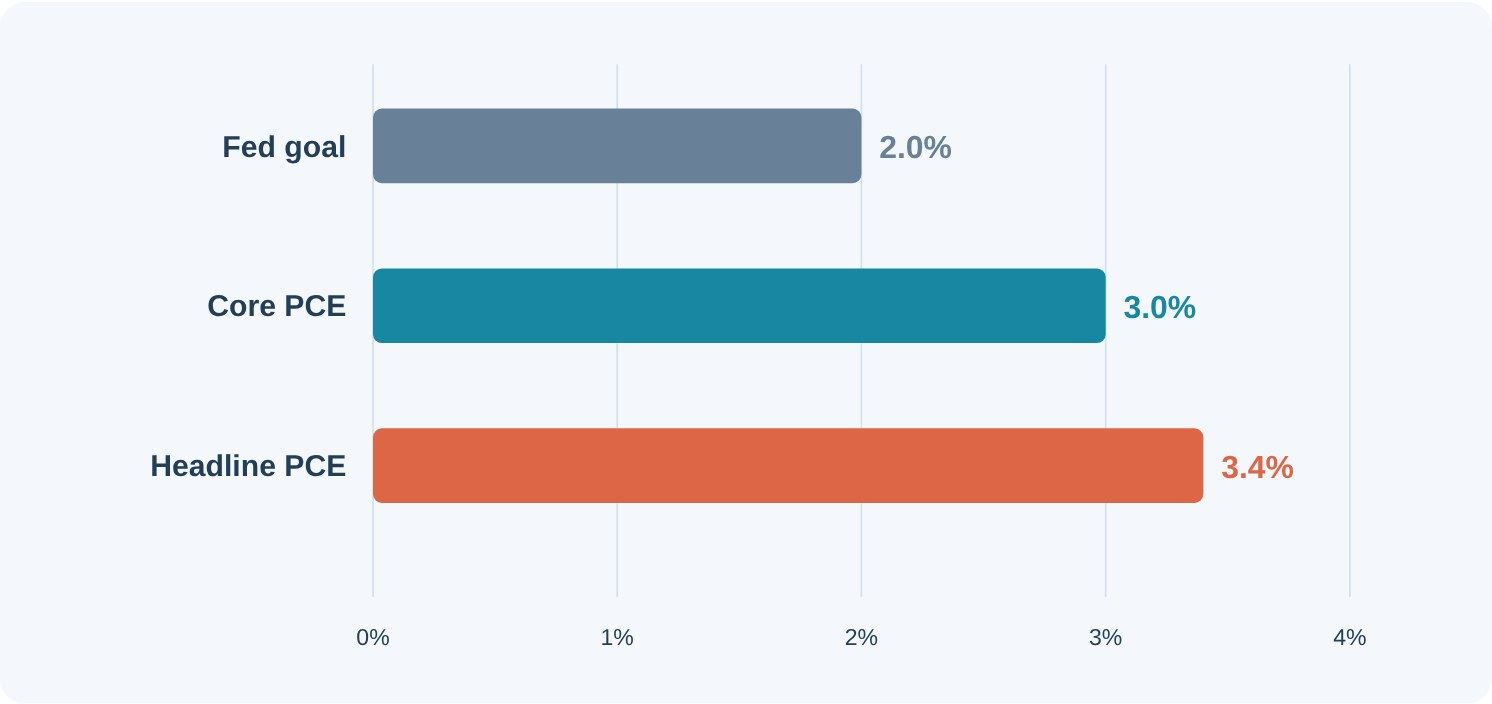
HEADLINE PCE3.4%August • annual
CORE PCE3.0%August • annual
FED INFLATION GOAL2.0%Longer-run objective
THE RATE UPDATE • VISUAL EXPLAINER
Inflation is still above the Fed’s goal
Latest verified annual PCE readings: August 2026.
Sources: BEA, August PCE released September 30; Federal Reserve longer-run inflation goal. The goal applies to headline PCE over time.
THE RATE UPDATE • BY THE NUMBERS
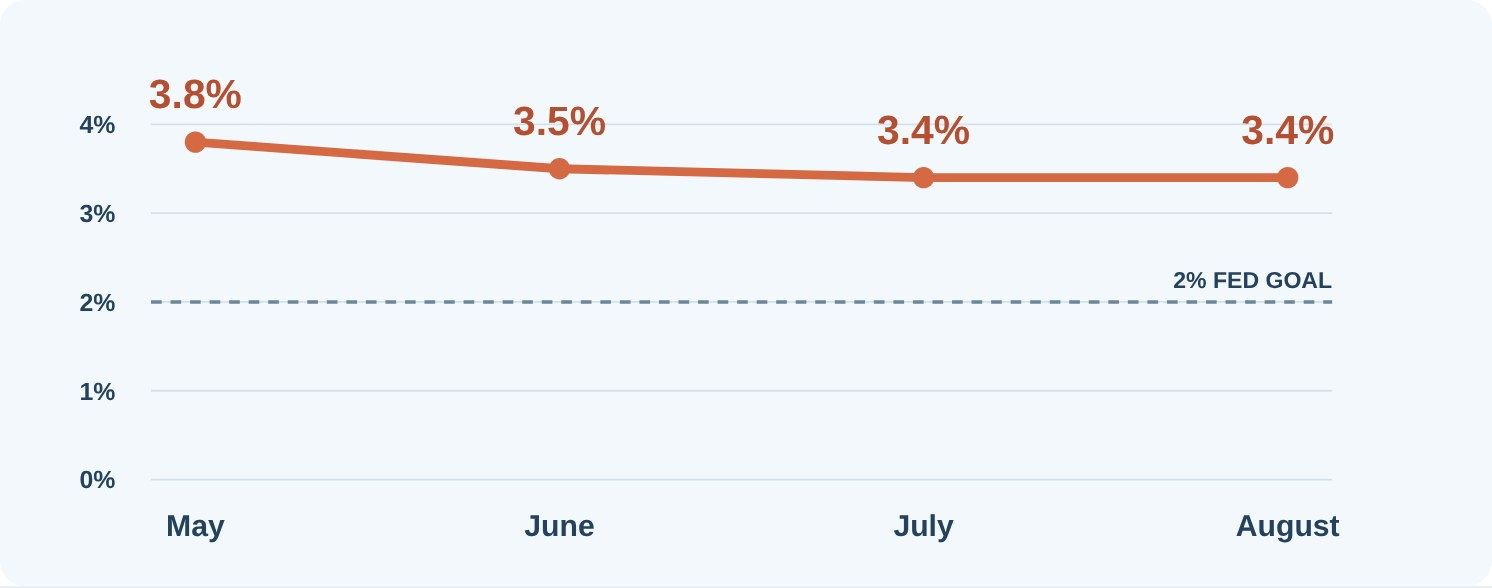
Inflation eased. Then stalled.
Headline PCE • annual change • 2026
Source: BEA PCE index page. May 3.8%; June 3.5%; July 3.4%; August 3.4%. Latest release September 30.
UNEMPLOYMENT4.2%September
U.S. PAYROLLS+29,000September • BLS
THE RATE UPDATE • BY THE NUMBERS
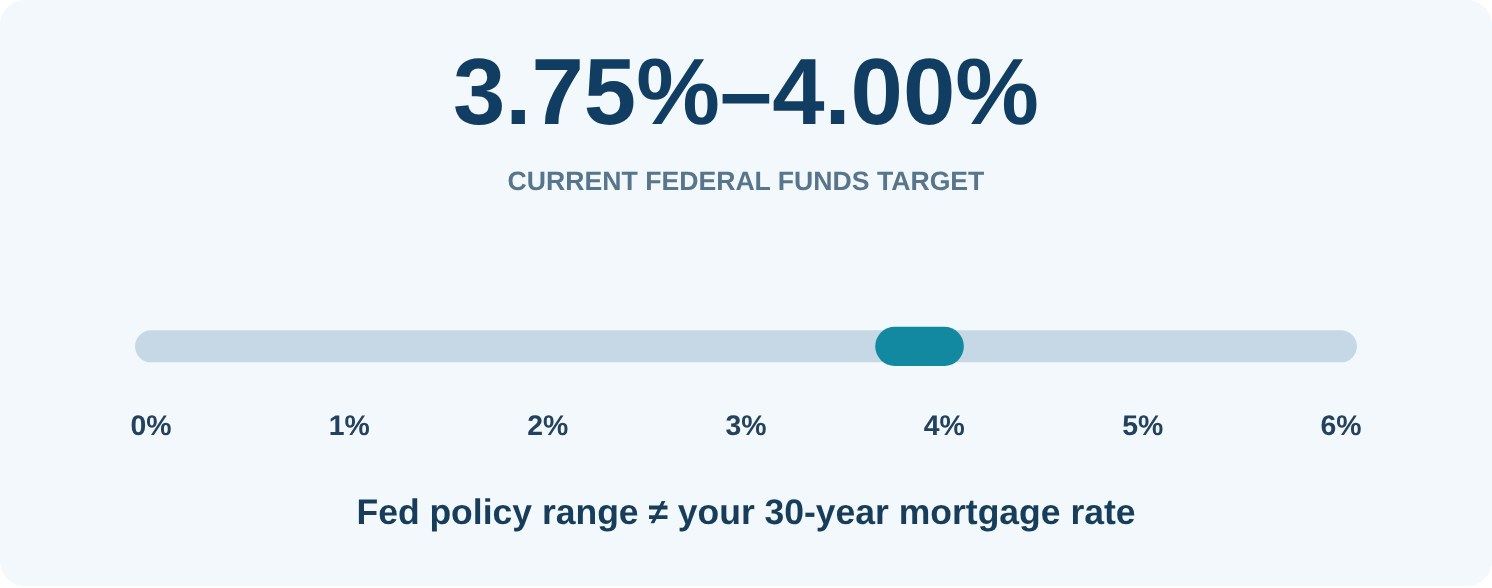
The Fed’s starting point
Target range established September 16, 2026.
Source: Federal Reserve September 16 statement. Scale is a reference axis, not a forecast or a historical range.
TAKEAWAY The Fed targets 2% inflation. It has no fixed unemployment target.
Latest verified releases: PCE September 30; jobs October 2; Fed policy September 16. [3][4][5][6]
05 • FEDWATCH
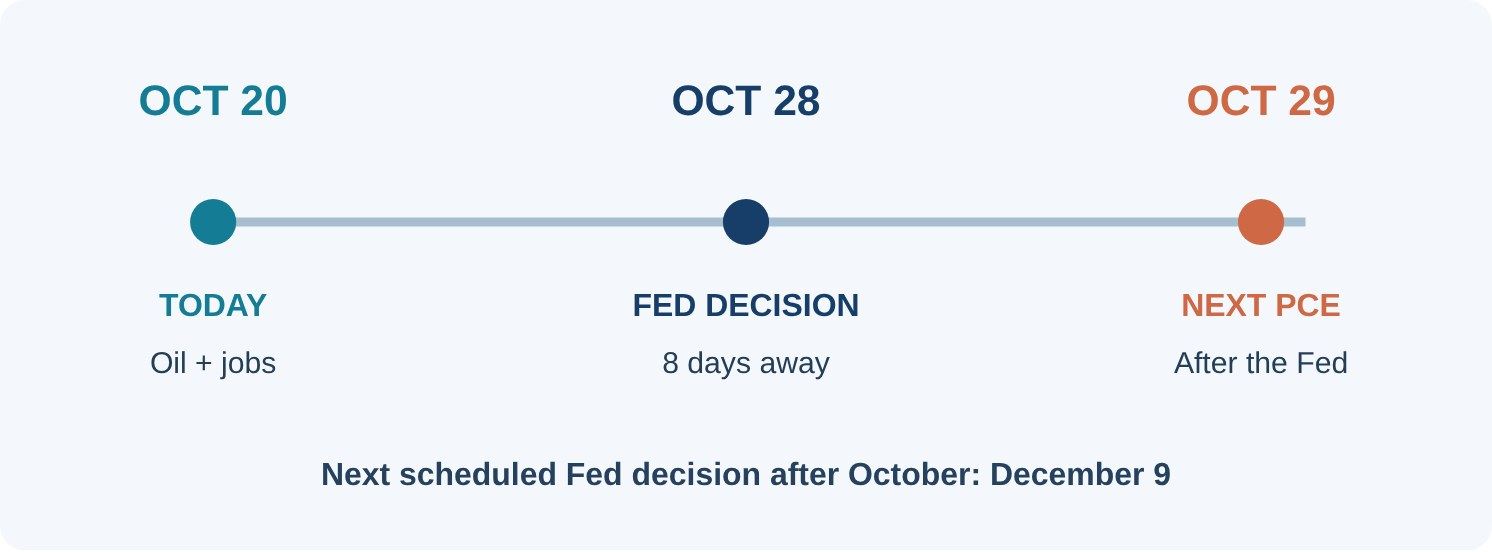
The next dates that matter.
THE RATE UPDATE • VISUAL EXPLAINER
The order of events matters
The next PCE report arrives after the October policy decision.
Sources: Federal Reserve meeting calendar; BEA release schedule. Live CME FedWatch percentages are not available in this edition.
OCT 28Cut • Pause • Hike
DEC 9Year-end target range
EARLY 2027Next direction of policy
Exact live probabilities were unavailable. No percentages have been estimated or invented.
Dan Frio | NMLS #246527 | PBT Bancorp | NMLS #257781 | Equal Housing Lender 524 Main St, Hazard, KY 41701
Dan Frio is a federally registered mortgage loan officer with PBT Bancorp. Mortgage assistance is available in the states and jurisdictions served by the bank. Mortgage products are originated by PBT Bancorp, NMLS #257781. Rates, lender pricing and refinancing are not guaranteed. This is not a commitment to lend.
* Specific loan program availability and requirements may vary. Please get in touch with your mortgage advisor for more information.